Europe’s Storage Market Nearly Doubles as Home and C&I Stock Piles Up
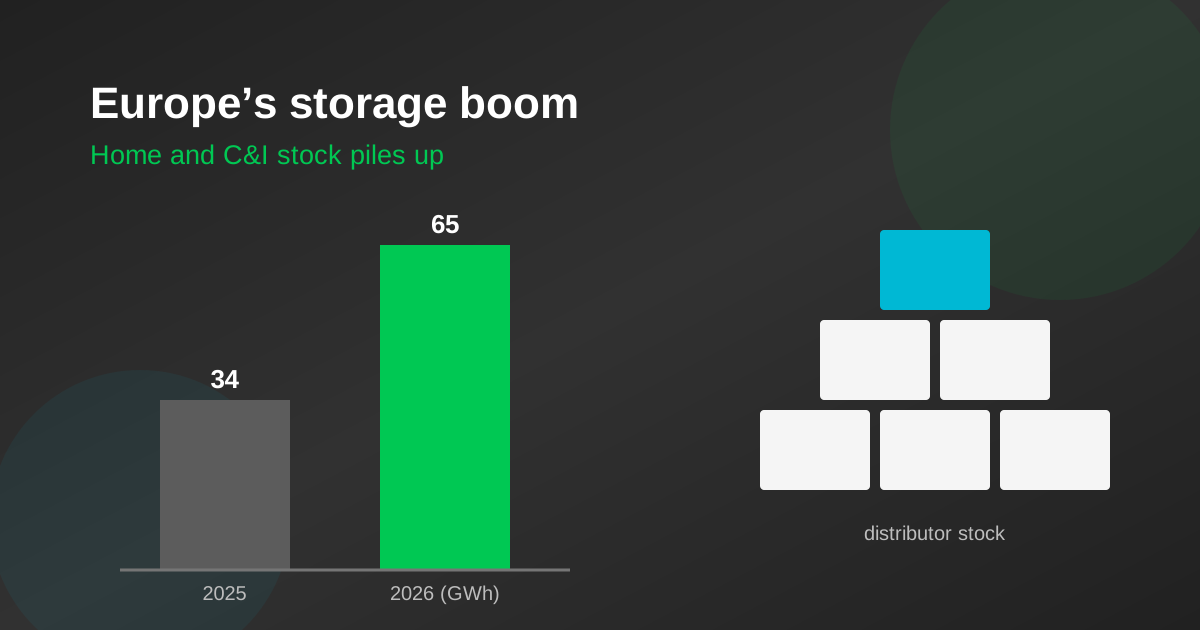
EUPD Research sees European installations rising from 34 GWh to 65 GWh this year. Its analyst also warns of a temporary oversupply of home and C&I systems as shipments race China’s rebate cut.
Published: 11 October 2026
Industry · 3 min read
A record year with two different stories inside it
Written 11 October 2026, on EUPD Research’s market outlook as published by pv magazine (6 October), an interview with EUPD analyst Ali Arfa in ESS News (9 October), and EUPD’s own release of 7 September.
Europe will install far more battery storage this year than last. In an article for pv magazine on 6 October, EUPD Research projects installations across the EU, UK, Switzerland, Norway and Ukraine rising from 34 GWh in 2025 to 65 GWh in 2026. About 44 GWh of that is utility-scale, which EUPD calls a record and “the industry’s main growth engine”. Residential adds roughly 15 GWh.
The headline number has moved. EUPD’s own release of 7 September put the market at 32 GWh in 2025 rising to 57 GWh in 2026, a 78 per cent increase. The October article does not explain the difference. Either way, the direction is the same: Europe’s storage market is close to doubling in a year.
Where the stock is piling up
The more useful part is what sits under the total. In ESS News on 9 October, Arfa described a split between segments. Utility-scale systems are usually built to a specific order, so they rarely sit in warehouses. Home and smaller commercial systems pass through distributors, wholesalers and installers, and stock can build at each step.
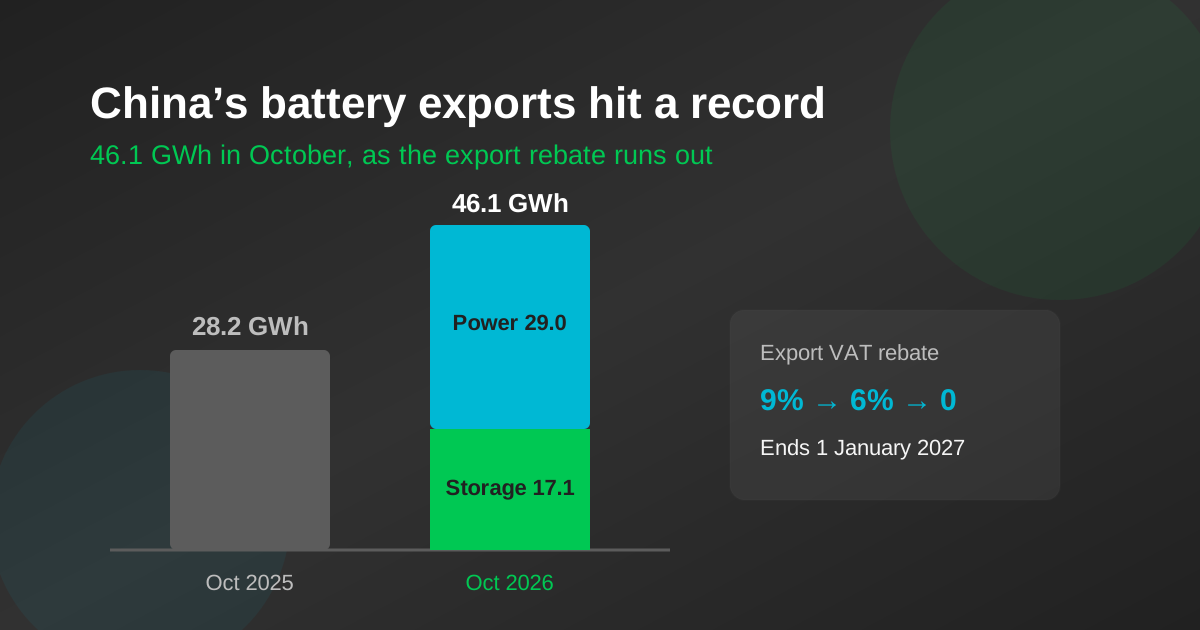
He links the build-up to China’s export tax rebate on battery products, which ESS News reports is falling from 9 per cent to 6 per cent and ending in January 2027. That pulls shipments forward. “That is why we see huge shipments that are basically coming to different places, especially Europe, before that time,” Arfa said. Some manufacturers’ shipment plans suggest more than the market can absorb, and installers are a bottleneck.
- •Greatest risk of temporary oversupply: residential and C&I, in Q4 2026 and Q1 2027 (Arfa, ESS News)
- •Unconfirmed reports of German wholesalers selling below manufacturers’ direct prices (ESS News)
- •Utility-scale prices expected to stay roughly stable, with no significant fall in the next two to three years (Arfa)
- •Residential installations in 2026 put at 15–17 GWh in ESS News, against about 15 GWh in the pv magazine article
Two prices, not one. A glut in home and commercial systems sold through distributors says little about what a utility-scale buyer pays. Arfa expects the first to soften and the second to hold. The second half fits what we reported at the end of September: storage cell prices held while lithium fell.
China’s share is not about to change
Arfa does not expect the supply chain to look very different in two years. ESS News quotes his estimates: Chinese firms hold about 80–90 per cent of battery cell manufacturing and about 70–75 per cent of pack production. In the long run he expects Chinese manufacturers to build more capacity in Europe itself. “In the long term, what I see is these Chinese manufacturers coming to you,” he said.
What it means for this business
Europe is not India, and a European distributor glut does not set prices here. But the mechanism Arfa describes, a tax deadline in China pulling shipments forward, applies to any importing market.
- •If Chinese export rebates end in January 2027, Indian importers of cells and packs face the same incentive to buy ahead, and the same risk of a price step afterwards
- •Cheap stock clearing through a distribution channel is not the same as a falling cost of supply. A quote is only as good as its warranty and the supplier behind it
- •For a factory comparing storage quotes, the useful question is which price you are being shown: a spot clearance or a supply contract
Our earlier pieces on why storage cell prices held while lithium fell and on the spread in system prices between markets give the cost side. Our commercial storage page covers how we approach C&I systems.
Sources
Reporting this piece draws on. Figures were correct as published; scheme terms and commodity prices move.
- What’s driving Europe’s battery boom? Insights from EUPD Research’s Business Climate Survey and Storage Reportpv magazine · 6 October 2026
- European storage inventories on the riseESS News · 9 October 2026
- Europe’s Battery Storage Boom Accelerates as 2026 Installations Set to Jump 78% YoYEUPD Research · 7 September 2026
Frequently asked questions
How much battery storage will Europe install in 2026?+
EUPD Research, writing in pv magazine on 6 October 2026, projects 65 GWh across the EU, UK, Switzerland, Norway and Ukraine, up from 34 GWh in 2025, with about 44 GWh utility-scale. Its own September release gave lower figures, 57 GWh against 32 GWh.
Why are home and C&I batteries piling up in Europe?+
EUPD analyst Ali Arfa told ESS News that China’s export tax rebate on battery products, falling from 9 to 6 per cent and ending in January 2027, is pulling shipments forward. Home and smaller commercial systems pass through distributors and installers, where stock can build.
Will utility-scale battery prices fall too?+
Arfa expects utility-scale prices to stay roughly stable, with no significant fall over the next two to three years. Those systems are usually built to specific orders, so they are less exposed to inventory build-up.
Want this applied to your own numbers?
Every solution page carries a calculator that shows its own arithmetic — storage savings, lithium against lead-acid, and home pack sizing.